Your Income Goes In
Your pay is deposited into the account, and the balance you owe drops right away instead of sitting in a separate bank account.

Brokerage #13763
Being mortgage free sooner is a goal many homeowners share, and the way you pay can change how much interest you carry. We teach you the options, from faster payment schedules to extra payments and, with some lenders, all-in-one accounts, and show you what your lender allows. lendsimpl is FSRA Brokerage #13763.
 5.0 on GoogleFSRA Brokerage #13763Ontario-wide
Where are you at right now?
No obligation
Pay half your monthly payment biweekly. That adds up to 13 monthly payments a year instead of 12, and the extra goes straight to your balance.
Many lenders let you put extra money on your balance once or more a year, up to a limit they set. A bonus, a refund or savings can each do the job.
Raising each payment by a set amount, within what your lender allows, sends more to principal each month without a big one-time effort.
Tax refunds, bonuses, an inheritance or overtime pay can go straight to your mortgage balance. Tell your lender the extra is for principal.
Extra money applied earlier in the year or earlier in the term reduces your balance sooner, so less interest builds on it.
Renewal is a natural time to choose a shorter payoff timeline. Your payment goes up, so we check it fits your budget first.
If your rate comes in lower at renewal, you can keep paying the old amount. The difference goes to principal, and your balance falls faster.
With some lenders, your pay goes into one account that combines your mortgage, a line of credit and your everyday banking, so your balance drops the day you are paid. It suits some households and not others, and we explain how it would work for you.
Half your monthly payment biweekly, which adds up to one extra monthly payment a year. Check with your lender: whether your lender offers it and how the extra is applied.
Extra money straight to your balance, up to your lender's limit. Check with your lender: your limit, the allowed dates and whether you must name it as principal.
Raises each payment by a set amount or percentage. Check with your lender: the increase your lender allows and whether it carries into your renewal.
A shorter payoff timeline, usually chosen at renewal, with a higher payment. Check with your lender: whether it fits your budget and what your lender allows at renewal.
Your pay goes into one account that combines your mortgage and everyday banking, and interest is worked out daily. Check with your lender: whether your lender offers one, how the line of credit rate works and what fees apply.
5.0 on Google
Verified reviews
13 payments a year
With accelerated biweekly
50+
Lenders compared
30 minutes
Call with a licensed broker

FSRA Licensed
50+ lender network
Monthly means 12 payments a year. Regular biweekly takes your annual payment total and divides it by 26, so you pay biweekly but the yearly total stays the same. Accelerated biweekly halves your monthly payment and pays that amount 26 times a year, which adds up to about one extra monthly payment a year. That extra goes to your balance. Not all lenders offer it, and some apply it differently, so we check before you choose.
You'll be talking to
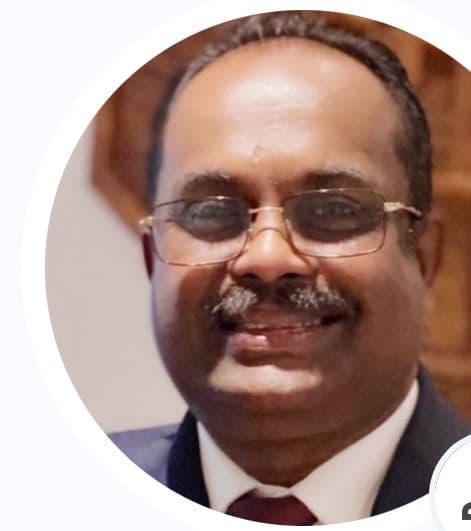 Tissa RatnayakeLicensed Mortgage Broker
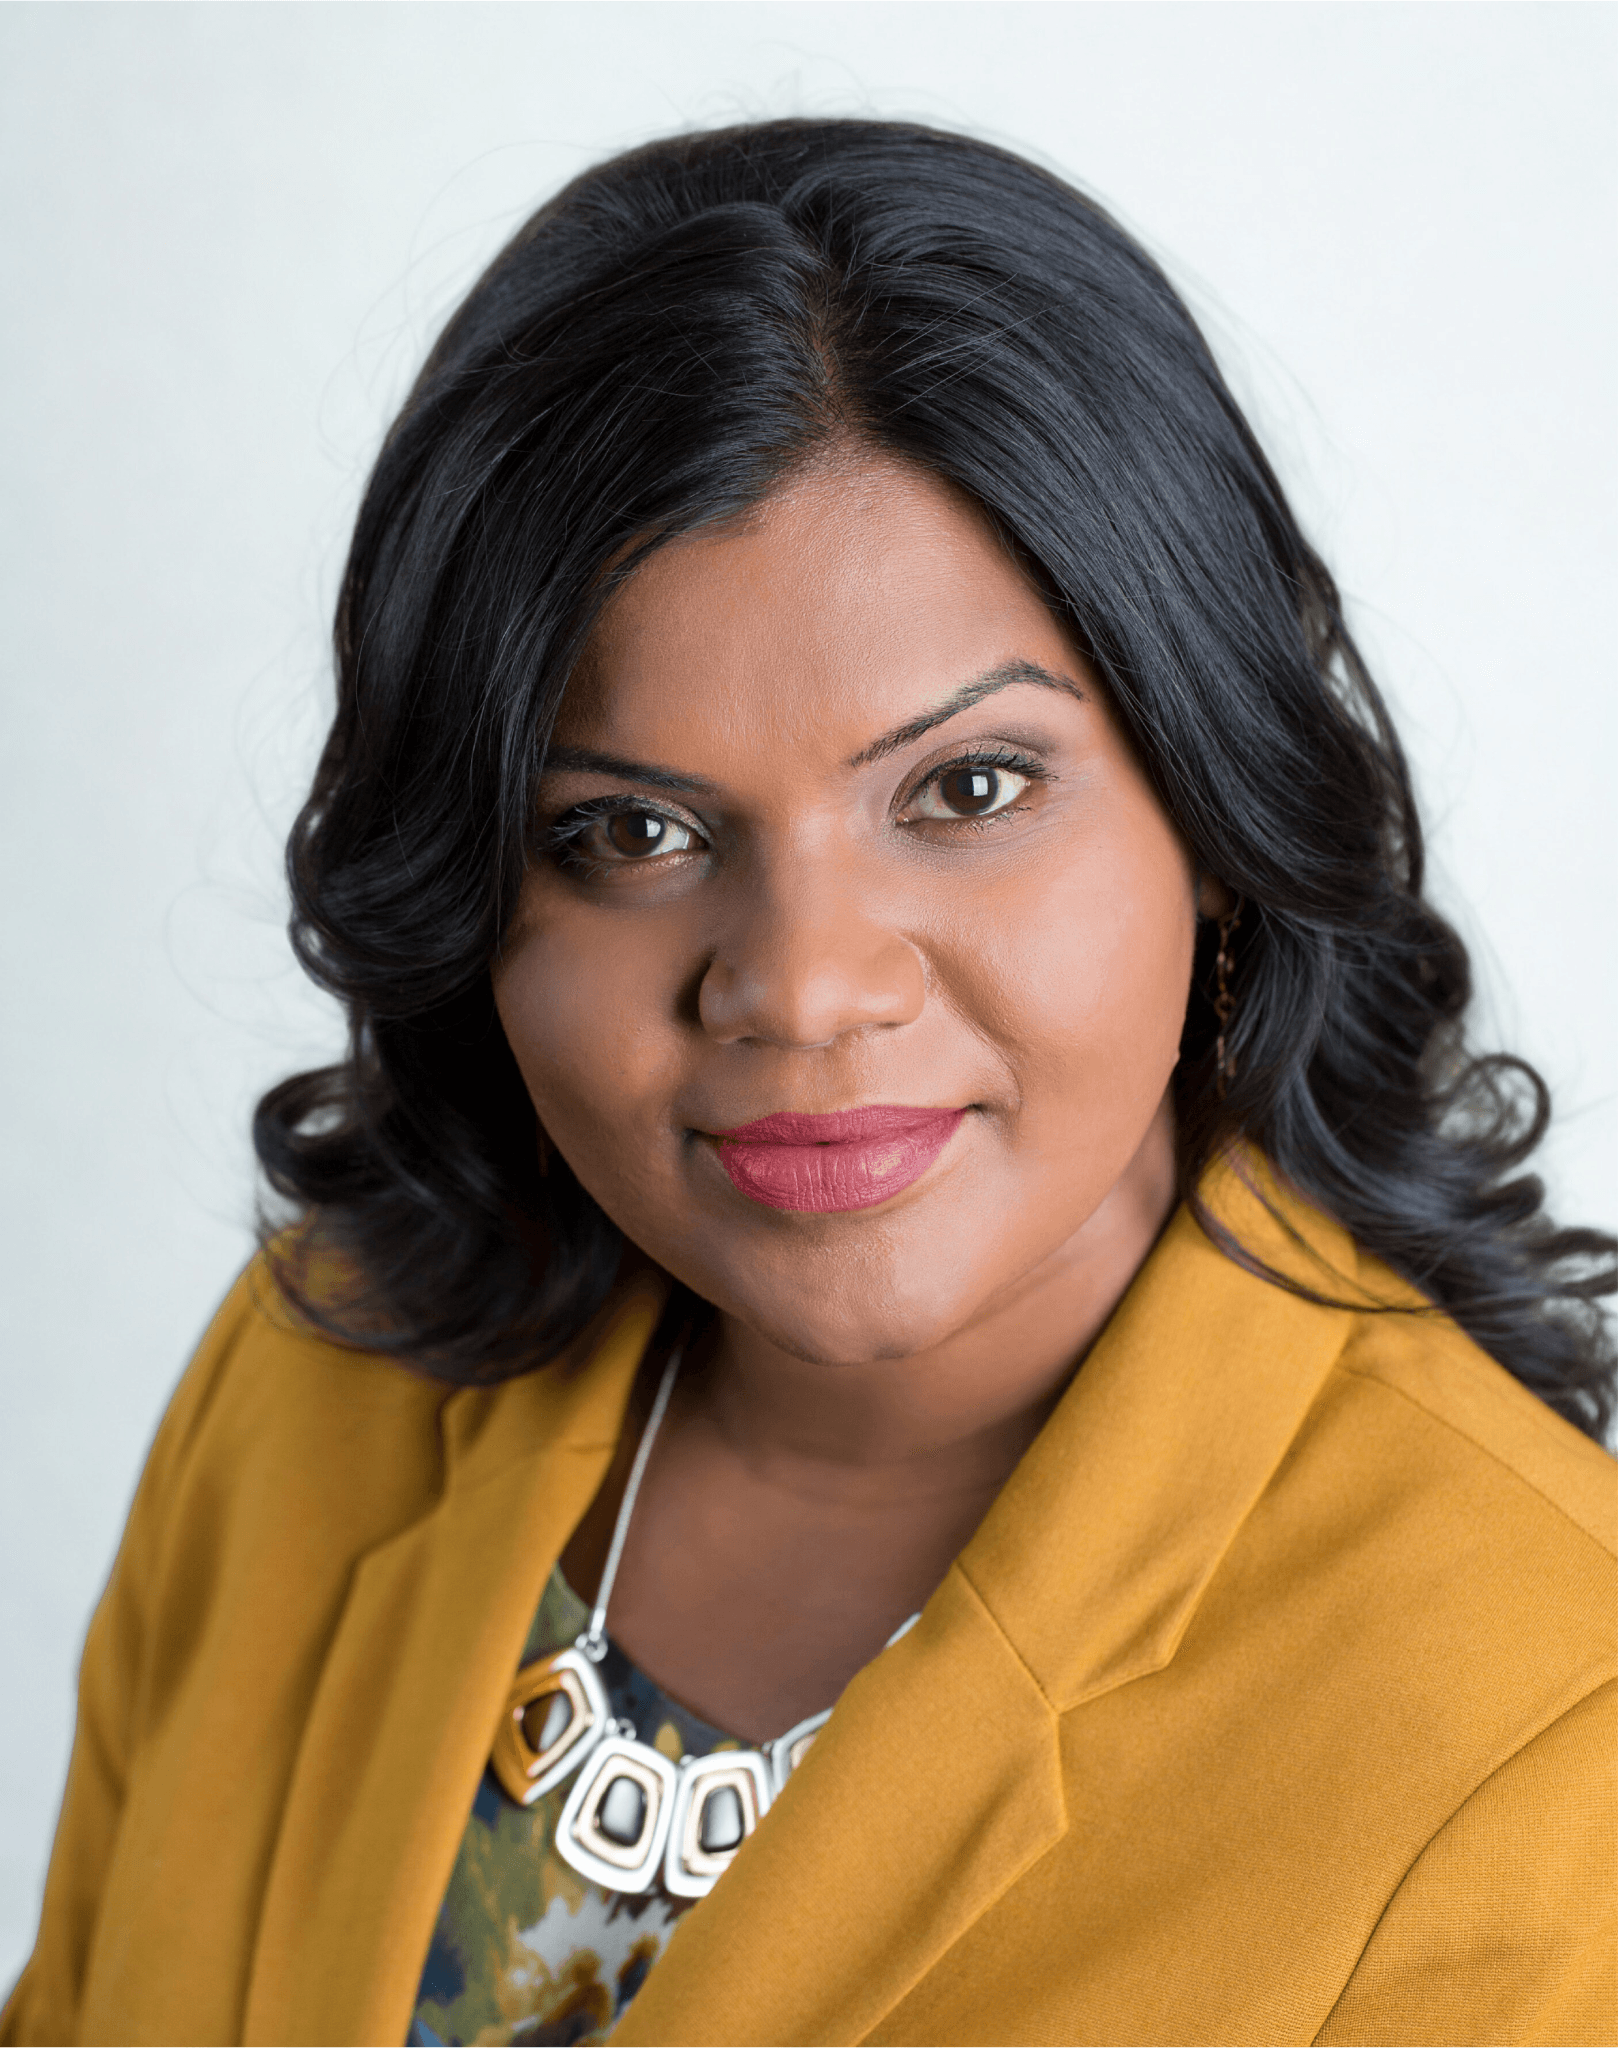 Anne XavierLicensed Mortgage Broker
Not a call centre, real people, individually FSRA-licensed.
Most closed mortgages let you pay down a set amount or percentage of your balance each year without a penalty. The limit varies by lender, and unused room usually does not carry over to the next year.
Many lenders let you raise your regular payment by a set percentage without a penalty. The extra goes to principal.
Some products let you double a payment now and then. Not all products include this.
Paying more than your privileges allow on a closed mortgage can trigger a prepayment penalty. For fixed rates it is generally the greater of three months' interest or the interest rate differential, and variable rates usually carry three months' interest. Confirm your privileges with your lender before you make extra payments.
5.0/5 average rating on Google
“Damien Atapattu made my mortgage process completely stress‑free. He prepared all documents ahead of time and clearly understands lender, lawyer, and appraisal requirements. A friendly, energetic professional who gets results.”
Aruna Bandaranayake
Google review · 6 mo ago
“Highly recommend! Damien took a lot of time to explain the terms thoroughly. He is very knowledgeable and trustworthy. Looking forward to working with him again!”
Tommy Ravindran
Google review · 7 mo ago
“Shamal was amazing throughout the whole process. He is very helpful, knowledgeable and patient. If you need a good reliable mortgage broker he is the guy! He will find you the best solution.”
Avy Loc
Google review · 8 mo ago
“Highly recommend. Damien was excellent throughout everything. Walking us through everything step by step. He was extremely well prepared and well versed in everything we needed to get a mortgage at a great rate.”
John Abraham
Google review · 8 mo ago
“I had a great experience working with Damien. He helped me secure a very competitive mortgage rate through Scotiabank and made the entire process smooth and stress-free. He was knowledgeable, transparent, and always quick to respond to my questions. I highly recommend him.”
Rz
Google review · 9 mo ago
“I approached lendsimpl for some financing and was amazed at the quality and time frame of service. Within a matter of days my deal was completed. Thanks to Damien and the team for expediting my business so efficiently. I highly recommend them for your financing needs. Five stars from us.”
Sunrise Meadows
Google review · 11 mo ago
Some lenders offer one account that combines your mortgage, a line of credit and your everyday banking. It is built for homeowners who want their money to work against their mortgage balance. It is not a fit for everyone, so here is how it works and what to weigh.
Your pay is deposited into the account, and the balance you owe drops right away instead of sitting in a separate bank account.
Interest is calculated on the balance each day, so money sitting in the account for even a few days can reduce the interest you pay. How much depends on your balance, your spending and your rate.
As you pay the balance down, you can usually borrow it back up to your limit, so your cash is not locked away. The limit and the rules are set by your lender.
The line of credit part of the account may carry a rate that moves with your lender's prime rate, easy access can make it easier to spend, and qualifying rules apply. Not every lender offers one, and any fee that applies to your file is disclosed in writing before you commit.
It can suit homeowners with steady income and a clear spending plan. We explain how it would work on your numbers before you decide.
Straight answers on biweekly payments, prepayment privileges, and whether to pay down your mortgage or invest, so you know exactly what fits your situation.
Have a question we didn't answer?
Our licensed broker team is happy to help.
With some lenders, an all-in-one account combines your mortgage, a line of credit and your everyday banking. Your pay is deposited into it, your balance drops right away, and interest is calculated daily on what you owe, so the money you hold there can reduce the interest you pay. You can usually borrow back up to your limit. The line of credit part may carry a rate that moves with prime, and easy access takes discipline, so we explain how it would work for you before you decide. Without one, you can still speed things up with accelerated payments, extra payments and your prepayment privileges.
There is no single fastest way. Paying more, paying earlier and shortening your amortization all reduce the interest you carry. What you can do depends on your lender's privileges and your budget, so we start with what your mortgage allows.
It depends on your goals, your comfort with risk, your mortgage terms and the registered account room you have. We are mortgage brokers, not financial advisors, so we show you what each mortgage option would do and you can weigh it with a financial professional.
Not every lender offers one, and qualifying rules apply. The rate on the line of credit part may move with your lender's prime rate, and being able to borrow back means you need a clear spending plan. Fees can apply, and any fee that applies to your file is disclosed in writing before you commit. It tends to suit steady earners who deposit their income into the account, and we compare it with a regular mortgage on your numbers.
Regular biweekly divides your annual payments by 26, so the yearly total is the same as monthly. Accelerated biweekly halves your monthly payment and pays it 26 times a year, which adds up to about one extra monthly payment a year.
They are the rights in your mortgage contract to pay extra without a penalty, such as an annual lump sum or a higher regular payment. The limits vary by lender and your contract sets them.
Not if you stay within your privileges. Going over them on a closed mortgage can trigger a penalty. Fixed rates generally use the greater of three months' interest or the interest rate differential, and variable rates usually use three months' interest. Check your contract first.
Usually, yes. Renewal is a common time to choose a shorter amortization, and your payment goes up when you do. We check that the new payment fits your budget before you decide.
You can usually keep paying the old amount. Because less of it goes to interest, more goes to your balance, and you pay the mortgage down faster.
Still have questions?
Talk to a licensed broker.
From downtown Toronto across the province, lendsimpl builds a payoff strategy wherever your mortgage is.
Important
Fees and disclosure
Any fee that applies to your file is disclosed in writing before you commit. What you can do depends on your lender, mortgage terms and budget.
Brokerage disclosure
lendsimpl is an FSRA-licensed mortgage brokerage (Brokerage #13763) helping Ontario homeowners build a personalized mortgage payoff strategy.
We look at your prepayment privileges, your renewal options and what your lender allows, then show you the moves that fit your budget.
Hello: I look forward to connecting with you. Tell us a bit about your situation and we'll walk through your options.