Bad Credit Borrower
Up to 75% LTV
A rough few years shows up on a credit report long after you've recovered from it. Private lenders don't read your history. They read your equity.

Brokerage #13763
You've paid into your home for years. Then the bank looks at a credit score, or a tax return that doesn't reflect what you actually earn, and says no. As if the equity you built isn't sitting right there. Private lenders start with the house instead. That's the whole difference.
 5.0 on GoogleFSRA Brokerage #13763Toronto & Ontario-wide
Takes about 30 seconds · No cost to compare your options · No obligation
Up to 75% LTV
7.75% per year
Up to 75% combined LTV
9.75% per year
Up to 65% LTV
Prime + 0.50% per year
Rates & approvals: Last updated: September 2026 · Verified against active lender rate sheets. Illustrative only — not an offer of credit. lendsimpl Mortgage Brokerage, FSRA #13763.
Speak with a licensed mortgage broker. Personalized review. We assess your situation and explain your private HELOC options.
Your home's value and available equity determine your HELOC limit. We arrange a quick appraisal (sometimes a desktop valuation suffices).
We match you with the best private lender from our network of 50+ lenders. We negotiate rates and terms on your behalf for the lowest cost.
Approval decisions often come within 24 to 48 hours. Funding follows once the appraisal is done and your lawyer has registered the HELOC against title. That usually takes one to two weeks in total. Your HELOC is set up as a revolving credit facility, so you draw and repay as you need to.
Banks decline on credit scores under 650, on irregular income, on debt ratios. Often without looking any further than that. Private lenders start with the property instead. If you own a home in Ontario with real equity in it, a private HELOC is worth looking at
Credit cards at 19.9% are built so the balance barely moves. Consolidating into a private HELOC at a lower blended rate, with interest only payments, buys you room to breathe and a plan to work to.
Banks want T4s, Notices of Assessment and employment letters. Private lenders put very little weight on income documentation and look at your home equity instead. Freelancers, contractors and business owners are among the most common private HELOC borrowers we work with.
Need $50K to $300K for renovations but can't qualify at the bank? A private HELOC gives you revolving access to fund projects in stages — you only pay interest on what you draw. No lump-sum commitment.
Use a private HELOC to fund a rental property down payment, business expansion, or financial investments. When used for income-producing purposes, the interest may be tax-deductible, speak with your accountant about your specific situation.
CRA arrears. A settlement date. A payment you can't miss. Banks take weeks just to reach a decision. Private lenders often decide within two days, and we push time sensitive files to the front.
Pension income alone doesn't always satisfy a bank's debt ratios, even with a mortgage-free or low-balance home. Private lenders look at your equity instead of running your retirement income through bank formulas.
5.0 on Google
Verified reviews
75%
Maximum LTV with private lenders (banks typically cap at 65%)
1st & 2nd
Mortgage positions available
#13763
FSRA-licensed brokerage, Ontario-wide

FSRA Licensed
Ontario-wide
A private Home Equity Line of Credit (HELOC) is a revolving credit facility secured against your home's equity, provided by private lenders instead of banks. Unlike traditional HELOCs that require excellent credit scores (650+), private HELOCs focus on the equity in your home — making them the ideal solution for borrowers rejected by banks.
You'll be talking to
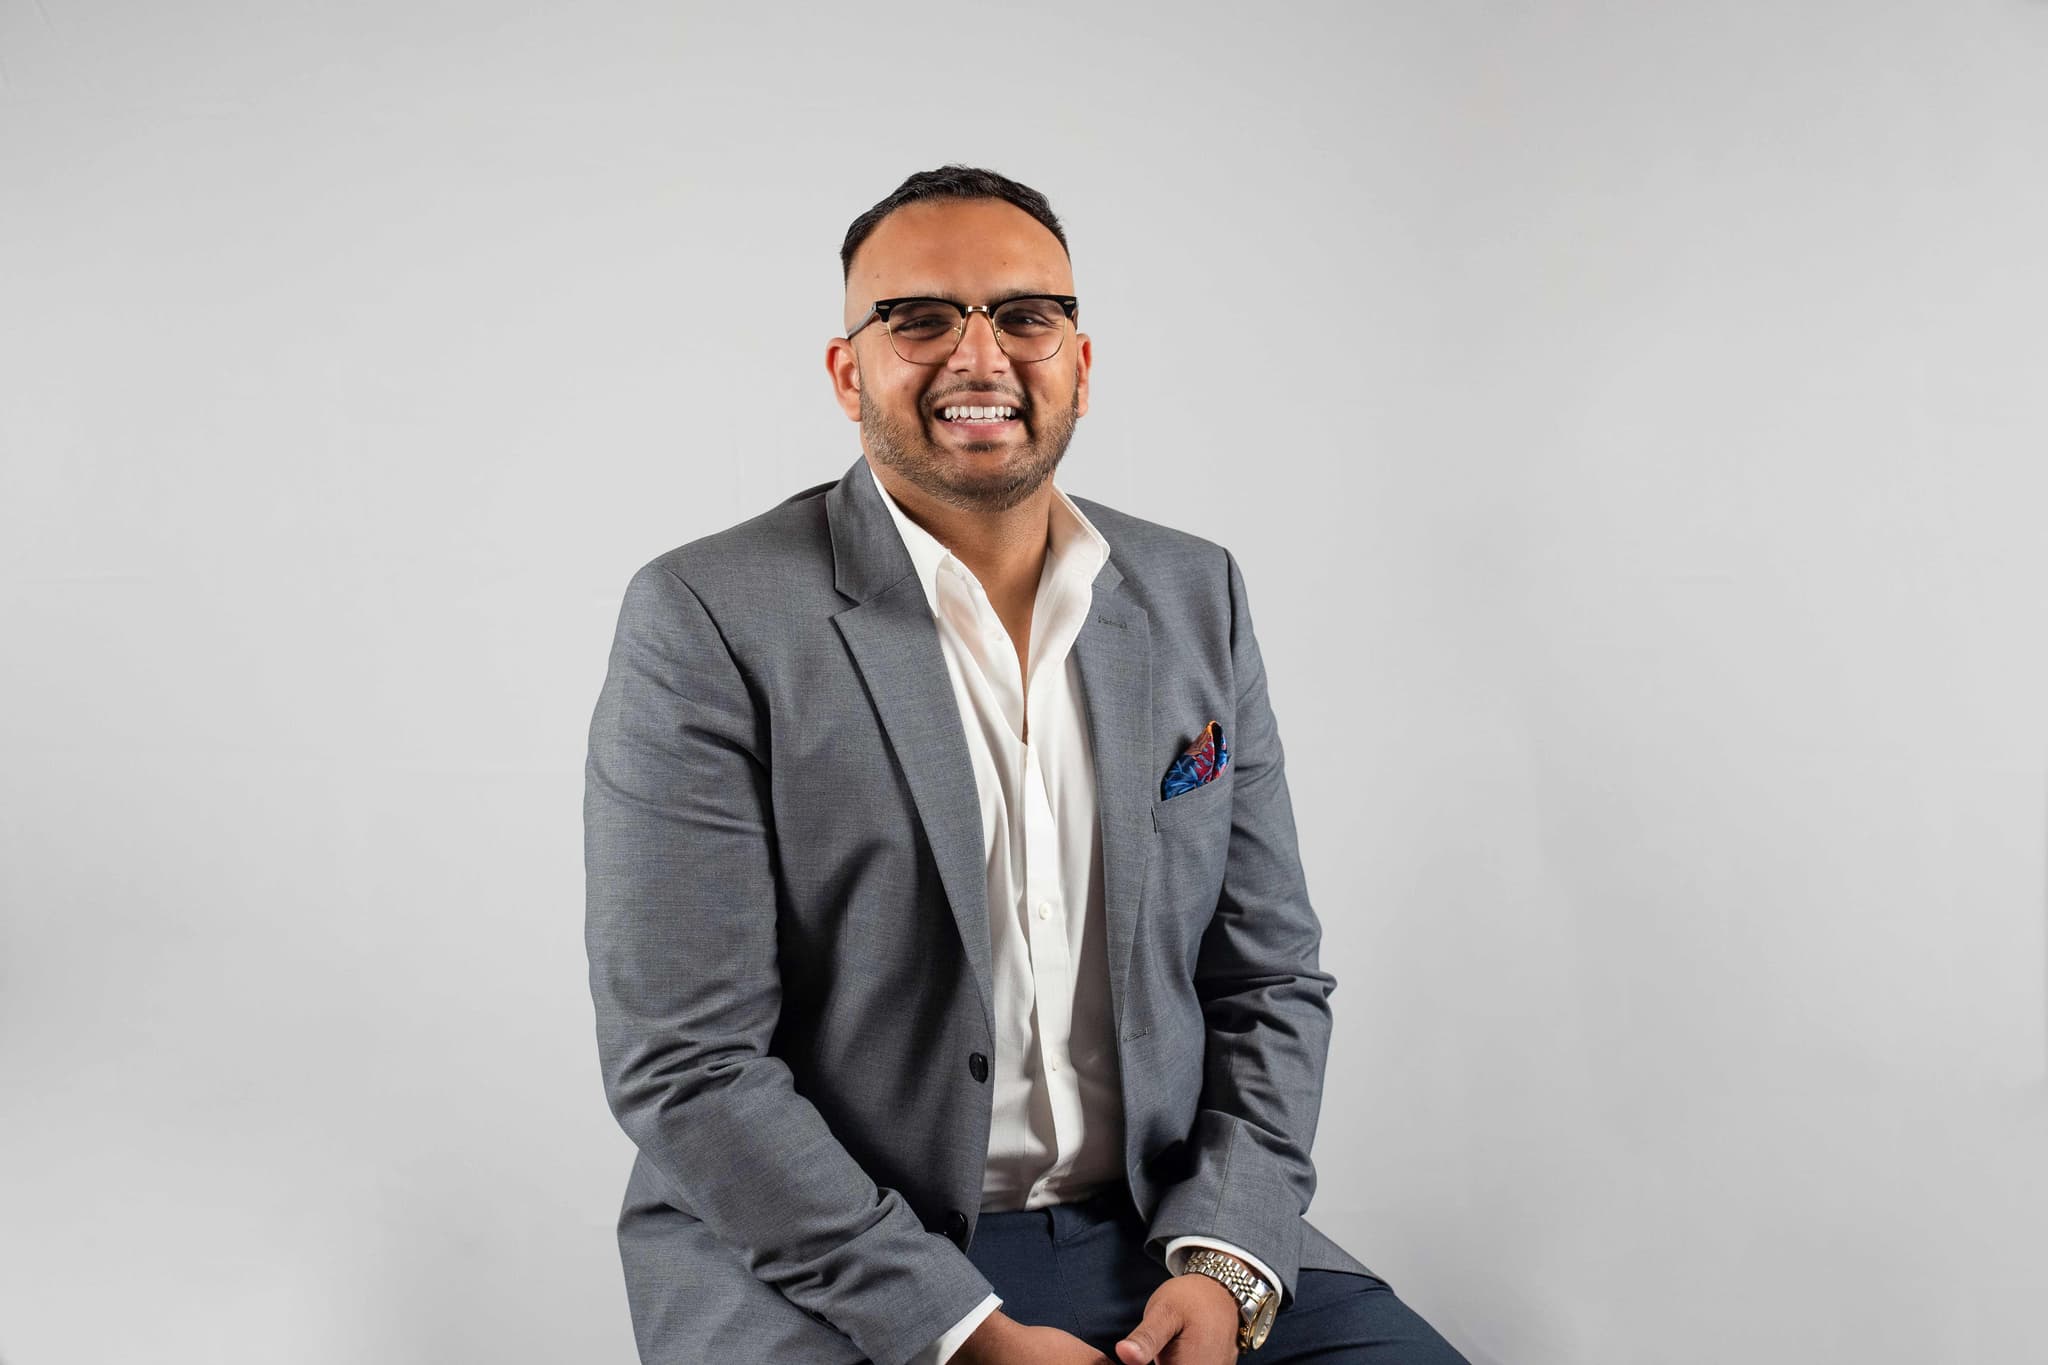 Damien AtapattuPrincipal Broker
Not a call centre, real people, individually FSRA-licensed.
lendsimpl is a Financial Services Regulatory Authority of Ontario–licensed brokerage. Every mortgage agent is individually licensed.
Any lender, broker, legal or appraisal fee that applies to your file is disclosed in writing before you commit to anything.
Your information is encrypted, handled with strict confidentiality, and shared only with the lenders relevant to your file.
Reviewing your options costs nothing and carries no obligation. You decide whether to move forward once you've seen the numbers.
5.0/5 average rating on Google
“Damien Atapattu made my mortgage process completely stress‑free. He prepared all documents ahead of time and clearly understands lender, lawyer, and appraisal requirements. A friendly, energetic professional who gets results.”
Aruna Bandaranayake
Google review · 5 mo ago
“Highly recommend! Damien took a lot of time to explain the terms thoroughly. He is very knowledgeable and trustworthy. Looking forward to working with him again!”
Tommy Ravindran
Google review · 6 mo ago
“Shamal was amazing throughout the whole process. He is very helpful, knowledgeable and patient. If you need a good reliable mortgage broker he is the guy! He will find you the best solution.”
Avy Loc
Google review · 7 mo ago
“Highly recommend. Damien was excellent throughout everything. Walking us through everything step by step. He was extremely well prepared and well versed in everything we needed to get a mortgage at a great rate.”
John Abraham
Google review · 7 mo ago
“I had a great experience working with Damien. He helped me secure a very competitive mortgage rate through Scotiabank and made the entire process smooth and stress-free. He was knowledgeable, transparent, and always quick to respond to my questions. I highly recommend him.”
Rz
Google review · 7 mo ago
“I approached lendsimpl for some financing and was amazed at the quality and time frame of service. Within a matter of days my deal was completed. Thanks to Damien and the team for expediting my business so efficiently. I highly recommend them for your financing needs. Five stars from us.”
Sunrise Meadows
Google review · 10 mo ago
A private HELOC (Home Equity Line of Credit) is a revolving credit line secured by your home equity, provided by private lenders instead of banks. Unlike bank HELOCs, private HELOCs have no minimum credit score, accept flexible income documentation, and are not subject to the federal stress test.
Best for bad credit borrowers, self-employed homeowners, and anyone rejected by banks. Available across Ontario.
Check eligibility →Private lenders in Ontario evaluate your application based on property value and available equity — not rigid income documentation or credit history. This means homeowners with bad credit, recent bankruptcy, CRA debt, or self-employment income can still access revolving credit at competitive private lending rates.
| Bank | Private | |
|---|---|---|
| Credit Score | 650+ required | Any — equity-based |
| Max LTV | Up to 65% | Up to 75% |
| Income Proof | Required | Flexible |
| Approval Speed | 2 to 4 weeks | Often 24 to 48 hours |
| Stress Test | Required | Not required |
| Payment Type | Interest-only | Interest-only |
| Best For | Strong credit | Rejected borrowers |
Private rates are higher, but you get access when banks say no.
Which situation sounds like you? Private HELOCs are built for real people in real situations — not just those with perfect credit.
Up to 75% LTV
A rough few years shows up on a credit report long after you've recovered from it. Private lenders don't read your history. They read your equity.
Up to 75% LTV
You built something. Then your accountant minimised your income for tax purposes, and the bank read that number as the whole story. Private lenders don't need your tax return to work out what your home is worth.
Up to 75% LTV
Some deadlines don't move. CRA arrears, a settlement date, a payment you can't miss. Banks take weeks to decide. Private lenders often decide in two days.
Up to 75% LTV
Four minimum payments, and none of them touching the balance. One payment at a lower rate isn't just cheaper. It's the first month in a long while that the number actually goes down.
Private HELOC qualification is simpler than you think. If you own a home with equity, you may be eligible regardless of credit or income — final approval depends on individual lender underwriting and property eligibility.
Residential property, house, townhouse, condo, standard and insurable. Your home is the collateral for the private HELOC. Some restrictions apply to rural or non-standard properties.
At least 25% equity (LTV below 75%). The more equity you have, the better rates and higher limits you'll receive.
Bad credit, bankruptcy, consumer proposals and CRA liens are all considered. Approval still depends on the lender's own underwriting and whether the property qualifies.
Self-employed, retired, unemployed, disability income, no T4s or NOAs needed for most private HELOCs.
| Min. Credit Score | No minimum |
|---|---|
| Min. Equity | 25% (75% LTV) |
| Income Proof | Flexible. Most files need no T4 or NOA. |
| Approval Decision | Often 24 to 48 hours |
| Term Length | 1 to 3 years |
| Payment Type | Interest-only |
| Max HELOC Amount | No set limit |
We believe in transparency. Here's the honest truth about private HELOCs — the good and the trade-offs.
Bad credit, bankruptcy, consumer proposals — private lenders evaluate equity, not your credit bureau.
Banks take two to four weeks just to give you an answer. Private lenders often decide within 24 to 48 hours, with funding once the appraisal and legal work are finished
Lower monthly payments — you only pay interest on the amount drawn, preserving cash flow.
Access more equity than bank HELOCs (capped at 65%). More equity = more borrowing power.
Self-employed? Irregular income? Private lenders don't require T4s, NOAs, or employment letters.
Draw, repay, and redraw as needed. Only pay interest on what you use. Flexible like a credit card.
Private HELOC rates run higher than bank HELOCs — see the rate comparison above. The trade-off is access.
Private HELOCs are typically 1 to 3 year terms. The goal: rebuild credit and refinance to a bank HELOC.
Expect a lender fee between 1% and 3%, plus our 1% broker fee. These are usually added to the HELOC balance rather than paid upfront, but they're a real cost of borrowing privately and worth factoring in.
Every private HELOC requires a property appraisal and legal fees at closing, on top of the lender fee. Appraisal cost varies by property and lender, your broker confirms the exact figure before you commit to anything. Legal fees typically run $1,500 to $2,500.
Like any HELOC, your home secures the credit line. Missed payments can put your property at risk of power of sale.
Private HELOCs come from a smaller lender pool than banks, so terms, fees, and conditions can vary more from lender to lender.
Most clients use a private HELOC as a bridge, accessing equity now, rebuilding credit over 12 to 24 months, then refinancing into a lower-rate bank HELOC. We help you plan the exit strategy from day one.
Private lending costs more than a bank. Anyone telling you otherwise is hiding something in the paperwork. Here is every fee, what it pays for, and what it adds up to, so you can decide with the real number in front of you.
| Cost | Typical range | Notes |
|---|---|---|
| Lender Fee | 1% to 3% of HELOC | One-time fee charged by the private lender. Often added to the HELOC balance. |
| Broker Fee | 1% of the HELOC amount | Charged on every private HELOC. Private lenders don't pay broker commissions the way banks do, so this one comes from you. We'd rather say that plainly than bury it. It covers sourcing your lender, negotiating the terms and managing the file through to funding, and it can usually be added to the HELOC balance. |
| Legal / Closing Costs | $1,500 to $2,500 | Covers the lawyer who registers the HELOC against your title. Required by law. |
| Appraisal Fee | Varies by property | Confirmed by your broker before you commit. Sometimes a desktop valuation suffices, which can lower the cost. |
| Title Insurance | $250 to $400 | Protects the lender against title defects. Standard on all mortgage/HELOC registrations. |
| Admin / Discharge Fee | $200 to $350 | Charged when the HELOC is eventually discharged or transferred. Varies by lender. |
Total typical cost example: Take a $150,000 private HELOC. The lender fee at 2% is $3,000. The broker fee at 1% is $1,500. Legal costs run around $2,000 and title insurance around $325. Appraisal cost varies and is confirmed before you commit. Most of these costs can be added to the HELOC balance rather than paid upfront. Your interest-only payment is the balance you draw multiplied by the rate in the cards above, divided by 12, and we calculate it for your file before you commit. Can fees be financed? Yes — in most cases, lender fees can be added directly to your private HELOC balance.
All fees vary by lender and situation. Your broker provides a full written cost disclosure before you sign anything.
Nobody wants a private HELOC forever, and we don't want that for you either. Most clients use one for 12 to 24 months while they rebuild, then refinance into a bank product. We plan that exit on day one, before you've signed anything.
Use your private HELOC to consolidate debts. Set up automatic bill payments. Begin building consistent payment history.
On-time payments start improving your score. Keep credit utilization below 30%. Avoid new hard credit inquiries.
Credit score approaches 600 to 650 range. Debt-to-income ratio improves. Your broker reviews bank eligibility quarterly.
Qualify for a lower-rate bank HELOC. Discharge the private HELOC. Save thousands annually on interest.
The Math: Private HELOC to Bank HELOC. A private HELOC is priced higher than a bank HELOC, so moving to a bank HELOC once your credit has been rebuilt can meaningfully lower your monthly interest cost while giving you permanent revolving credit access. We run the numbers for your file, using the current rates in the cards above, before you decide.
Learn About RefinancingNot sure a private HELOC is the right fit? Here are the most common alternatives our clients consider.
We're not a lead-gen site. lendsimpl is an FSRA-licensed mortgage brokerage with verified credentials and a track record of funded private HELOCs across Ontario.
| Regulatory Body | Financial Services Regulatory Authority of Ontario (FSRA) |
|---|---|
| Brokerage Licence | #13763 — Active & Verified |
| Broker Experience | Our brokers bring over 20 years in private and alternative lending |
| Private Lender Network | 50+ vetted lenders across Ontario |
| Specialization | Private & alternative lending |
| Average Approval Time | 24 to 48 hours. Funding follows once appraisal and legal work are complete, typically one to two weeks in total. |
Our Private HELOC Process: Every private HELOC we arrange follows a transparent, documented process. You will receive a detailed commitment letter outlining all rates, fees, and terms before you commit, with no pressure to proceed. Client Satisfaction: Every client gets a dedicated broker, full fee disclosure before signing, and a documented exit strategy. We focus on getting you back to bank-level rates within 12 to 24 months.
Everything Ontario homeowners need to know about private HELOCs — rates, eligibility, process, and more.
Have a question we didn't answer?
Our licensed broker team is happy to help.
A private HELOC is a revolving home equity line of credit provided by private lenders (individuals and Mortgage Investment Corporations) instead of banks. The key difference: private lenders approve based on your home equity, not credit score or income. This means borrowers with bad credit, bankruptcy, or self-employment income can access revolving credit that banks would deny.
Yes — bad credit is the most common reason borrowers choose private HELOCs. Private lenders don't have minimum credit score requirements. Regardless of your credit history, a recent bankruptcy, a consumer proposal, or collections, if you have at least 25% equity in your Ontario home, you may qualify for a private HELOC, subject to individual lender underwriting and property eligibility.
Approval decisions often come within 24 to 48 hours. Private lenders can move that quickly because they assess equity rather than running a full credit and income review. Funding takes longer. The appraisal has to be completed and your lawyer has to register the HELOC against title, so allow one to two weeks in total. For comparison, most banks take two to four weeks just to reach a decision.
Most private HELOC lenders place minimal weight on formal income verification. You typically don't need T4s, Notices of Assessment, employment letters, or pay stubs — approval is based primarily on your home equity. This makes private HELOCs a fit for self-employed borrowers, gig workers, retirees, and anyone with irregular or difficult-to-prove income.
Private HELOCs can go up to 75% of your home's appraised value (LTV), minus your existing mortgage. For example, a $900,000 home with a $400,000 mortgage could access up to $275,000 in private HELOC credit. There's no fixed dollar limit — it depends on your property and equity.
A private HELOC is revolving credit — you draw and repay as needed, like a credit card. You only pay interest on what you use. A private mortgage is a fixed lump-sum loan with set monthly payments. Choose a HELOC if you need flexible, ongoing access; choose a mortgage if you need one specific amount.
Yes, this is one of the most common uses. Consolidate high-interest credit cards, personal loans, and other debts into a single private HELOC payment at a lower blended rate.
Yes. Private lenders regularly approve borrowers with active consumer proposals, discharged bankruptcies, and even undischarged bankruptcies (with court permission). The primary consideration is your home equity, not your insolvency history.
You'll typically see a lender fee of 1% to 3% of the HELOC amount, our broker fee of 1%, legal and closing costs of $1,500 to $2,500, an appraisal fee that varies by property (confirmed before you commit), and title insurance at $250 to $400. Most of these can be added to the HELOC balance so you don't need cash upfront. You'll get the full written breakdown before committing to anything.
Yes — most private HELOCs require interest-only payments on the amount drawn. This keeps monthly payments significantly lower than principal-and-interest loans. You can make voluntary principal payments at any time to reduce your balance.
This is called an 'exit strategy' and we plan it from day one. Use the private HELOC for 12 to 24 months while rebuilding your credit. Pay bills on time, reduce debt ratios, and improve your score to 680+. Once qualified, refinance to a bank HELOC at a lower prime-based rate — saving significantly on interest.
Yes — private lenders offer HELOCs on investment properties, rental properties, and multi-unit buildings. Rates may be slightly higher than owner-occupied properties, but the same equity-based qualification applies, with minimal rental income documentation typically needed.
Yes. Private HELOCs carry a broker fee of 1% of the HELOC amount. Banks pay brokers a commission for bringing them business. Private lenders generally don't, so the fee comes from the borrower instead. On a $150,000 HELOC that's $1,500, and it can usually be added to the balance rather than paid out of pocket. Your first consultation is always free, and the exact fee is set out in writing in your commitment letter before you sign anything.
Banks pay brokers a commission for bringing them business. Private lenders generally don't, so the brokerage is paid by the borrower instead. It's the same work either way. Sourcing lenders, negotiating rate and terms, managing the file through to funding. Only the source of payment changes. If a brokerage tells you a private HELOC carries no broker fee at all, they're either not disclosing it or recovering it somewhere else.
We serve all of Ontario — Toronto, Mississauga, Brampton, Hamilton, Ottawa, London, Kitchener, Barrie, and every city and town in between. Our private lender network covers urban, suburban, and most rural Ontario properties.
Yes, if you're behind on mortgage payments and facing power of sale, a private HELOC can provide emergency funds to bring your mortgage current. This is one of the most urgent use cases we handle. Time is critical — contact us immediately if you're in this situation.
Still have questions?
Straight answers, no pressure.
We arrange private HELOCs for homeowners throughout Ontario.
Browse our private HELOC pages for cities across Ontario.
Important
Rates & approvals
Last updated: September 2026 · Verified against active lender rate sheets. Illustrative only — not an offer of credit. lendsimpl Mortgage Brokerage, FSRA #13763.
Brokerage disclosure
lendsimpl is an FSRA-licensed mortgage brokerage (Brokerage #13763) serving Toronto and Ontario. Rates, lender terms and approval timelines vary by borrower profile and lender. All applicable fees are disclosed in writing before you proceed, as required by FSRA regulations.
You've probably already had the conversation where someone said no. This one works differently. A licensed Ontario broker looks at your equity, tells you what's realistic, and tells you honestly if waiting is the better call.
Hello: I look forward to connecting with you. Tell us a bit about your situation and we'll walk through your options.
Quick links
lendsimpl is a Financial Services Regulatory Authority of Ontario (FSRA) licensed mortgage brokerage, Brokerage #13763. Nothing on this page is a mortgage offer, a rate quote or legal advice. Mortgage pricing varies by credit profile, down payment or equity, income type, property type, loan-to-value, term and lender, changes frequently, and is subject to lender approval and underwriting conditions, not every applicant qualifies for a lender’s lowest posted pricing. All applicable fees are disclosed in writing before you proceed. OAC. E&OE.
© 2026 lendsimpl corp. All rights reserved. Brokerage #13763. · Privacy Policy · Terms & Conditions